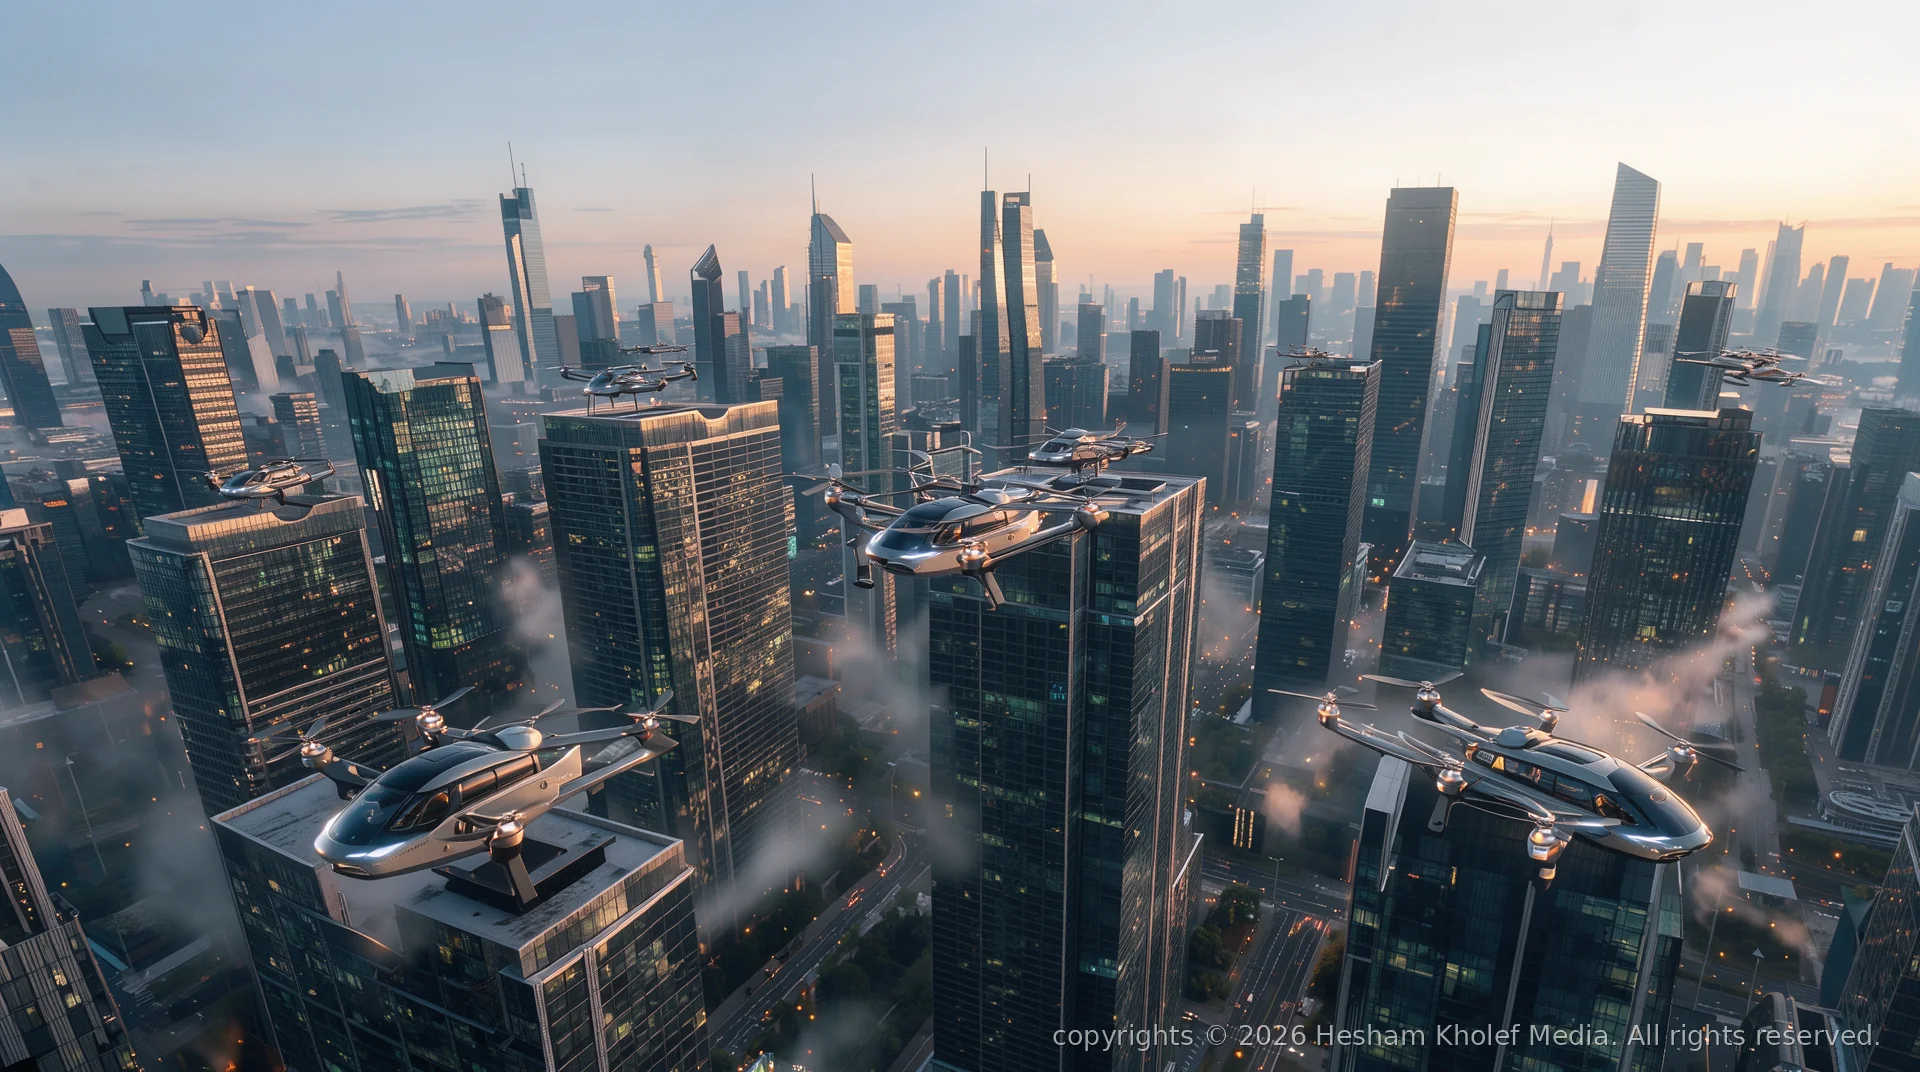
The Dream Takes Shape: From Jetsons to Joby

For generations, the flying car has been the ultimate symbol of a future perpetually ten years away. From the Jetsons to Blade Runner, popular culture promised us skies crisscrossed with personal aircraft, yet the reality remained stubbornly grounded. Today, that gap is finally closing. A new generation of electric vertical takeoff and landing vehicles — eVTOLs — has moved from concept renderings to certified prototypes carrying paying passengers in test corridors across three continents.
How eVTOLs Differ From Yesterday's Flying Cars
Unlike the roadable airplanes of the 1950s — heavy compromises that flew poorly and drove worse — modern eVTOLs are purpose-built for the air. They use distributed electric propulsion: anywhere from four to thirty-six small rotors, each independently controlled by flight computers that adjust thrust thousands of times per second. This architecture delivers three breakthroughs simultaneously: helicopter-like vertical lift, airplane-like cruise efficiency, and noise levels low enough for dense urban neighborhoods.
eVTOLs are not flying cars in the literal sense — they don't drive on roads. They are air taxis designed for short-hop urban and regional trips, typically 20–150 km, replacing an hour in traffic with a ten-minute flight.
The Contenders: Who's Closest to Commercial Service?
The leaderboard shifts monthly, but three names consistently appear at the top of certification trackers:
- Joby Aviation (USA) — Completed FAA Stage 4 certification; targeting 2025 launch with Delta Air Lines partnership for airport transfers.
- Archer Aviation (USA) — Midnight aircraft in FAA Stage 3; United Airlines has pre-ordered 200 units for Chicago and Newark routes.
- Volocopter (Germany) — VoloCity two-seater holds EASA SC-VTOL Type Certificate; preparing Paris Olympics demonstration flights.
Chinese players — AutoFlight, EHang, and TCab Tech — are running parallel certification paths with CAAC and have already logged thousands of passenger-carrying test flights in Shenzhen, Hefei, and Dubai.
The Infrastructure Puzzle: Vertiports, Not Airports

A flying car is useless without a place to land. The industry is converging on vertiports — compact, modular pads the size of a helipad but designed for high-throughput, automated operations. Think rooftops of parking garages, transit hubs, and purpose-built structures beside highways. NASA's Urban Air Mobility Grand Challenge has already validated traffic-management software that can deconflict hundreds of simultaneous flights in a single metropolitan corridor without human air-traffic controllers.
{
  "vertiport_spec": {
    "pad_diameter_m": 20,
    "charging_power_kw": 500,
    "turnaround_target_sec": 300,
    "simultaneous_operations": 4
  },
  "utm_integration": "U-Space / NASA UTM"
}
Regulation: The Invisible Runway
Technology is ahead of law — but the gap is narrowing. The FAA's MOSAIC (Modernization of Special Airworthiness Certification) rulemaking and EASA's SC-VTOL special condition create dedicated certification pathways for eVTOLs, distinct from both Part 23 airplanes and Part 27 helicopters. Both agencies now accept "equivalent level of safety" arguments backed by massive simulation datasets, accelerating approvals that once took a decade into three-to-five-year cycles.
"We are not building a new vehicle; we are building a new category of aviation. The rules must bend to the physics, not the other way around."
— JoeBen Bevirt, Founder & CEO, Joby Aviation
Noise: The Make-or-Break Metric
Community acceptance hinges on acoustics. Early prototypes sounded like swarms of angry hornets. Current production aircraft target 45–55 dBA at 150 m — quieter than a passing delivery truck and below the WHO night-time guideline for residential areas. Achieving this requires rotor tip speeds below 150 m/s, variable-RPM controllers, and acoustic liners borrowed from next-gen turbofans. Cities like Los Angeles, Singapore, and Munich have already written noise-based vertiport zoning into their master plans.
Economics: Will It Ever Be Affordable?

Launch pricing will be premium — $3–5 per passenger-mile, comparable to a Black Car service. But the cost curve is steep: battery energy density improves ~7% annually, composite airframes scale like automotive parts, and autonomy removes the single largest operating expense (pilots). McKinsey and Morgan Stanley both model a crossover to rideshare parity (~$1.50/mi) by the early 2030s, provided vertiport networks achieve critical density.
First-generation eVTOLs carry 4–5 passengers plus a pilot. True personal ownership — a vehicle in your driveway — remains a 2035+ prospect, constrained by battery weight, insurance frameworks, and the sheer complexity of untrained humans navigating three-dimensional traffic.
Autonomy: The Endgame Is Pilotless
Every major OEM is designing for Level 5 autonomy from day one. Current "piloted" launches are a regulatory stepping stone. The sensor suite — lidar, radar, optical flow cameras, and redundant GNSS/INS — already exceeds commercial airliner redundancy. The remaining hurdle is certification of AI decision-making under edge cases: bird strikes, GPS spoofing, vertiport conflicts. Simulators are logging millions of autonomous hours; regulators are developing "assurance cases" rather than traditional deterministic testing.
Environmental Ledger: Green Only If the Grid Is Green
eVTOLs emit zero operational CO₂, but lifecycle analysis matters. A 2024 NREL study found that charged on the current US grid mix, an eVTOL trip produces 40% less CO₂ per passenger-km than a gasoline car — but 20% more than a full electric sedan. The advantage widens dramatically on clean grids (France, Norway, Quebec) and narrows on coal-heavy ones. The industry is signing PPAs for dedicated renewable energy at vertiport sites to lock in green credentials.
Timeline: What Happens Next?
| Year | Milestone |
|---|---|
| 2025 | First paid passenger routes (NYC, Chicago, Paris, Dubai, Shenzhen) |
| 2026–2027 | Network expansion to 10+ cities; vertiport standards finalized |
| 2028–2030 | Autonomous certification begins; pricing approaches rideshare |
| 2030+ | Mass adoption; personal ownership models emerge |
Conclusion: The Sky Is No Longer the Limit
The flying car isn't arriving as a single miraculous vehicle. It's arriving as a system — aircraft, vertiports, airspace software, energy infrastructure, and regulatory frameworks — each piece clicking into place across the globe. We won't all learn to fly in the stick-and-rudder sense. Instead, we'll step into an autonomous cabin, tap a destination, and reclaim the hours traffic stole. The question isn't if urban air mobility becomes mundane; it's whether our cities will be ready when the rotors spin up over the morning commute.
Comments (0)